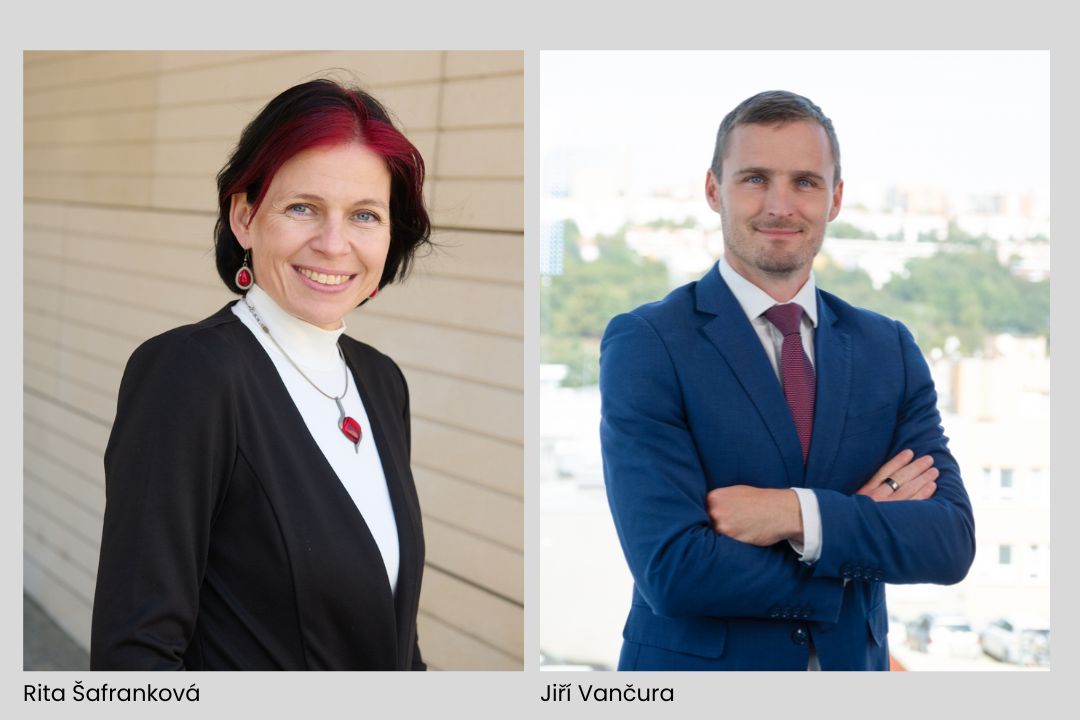
Trinity Bank operates a loan book of CZK 33 billion, almost all of which is credited to corporate real estate borrowers. It’s currently pursuing an aggressive expansion strategy through capital raises, the goal being to double its book to CZK 65 billion by 2029. That means handing out roughly CZK 15 billion annually, says Jiří Vančura, director of RE financing. I sat down with him and with Head of RE acquisitions Rita Šafránková to discuss Trinity’s strategy and goals. This was before another planned equity raise scheduled for this summer.
You’re winning a significant number of investment-loan tenders against the big banks. Why is that?
Vančura: It’s a combination of factors. Yesterday, I had a client here in the office and he told me were slightly worse on interest rate than a competitor. But he said they were happy with the service we offer and with our approach. These days we’re even competitive on pricing, but it’s also about the structures we’re open to and the flexibility. Sometimes we can offer higher LTV, but in general we’re still very conservative.
Šafránková: We have the advantage that we are a Czech bank. That means it’s Czech people decide about each loan, and they know the market here. We don’t have to send the final approval to France or Vienna, where they could have a different view. And we can decide quickly — one approval level, not three committees over several weeks. In selected cases we can get from first contact to drawdown in two months.
You say you’re conservative, so what that mean for you on LTV?
Vančura: In residential development we can do up to 90% LTV in some cases — combined with presale. With lower LTV we can go without presale. On investment loans, up to 80% depending on asset class.6
Šafránková: Of course, the 90% figure isn’t for a standard loan. We have to analyze each project carefully, because what actually protects you on investment loans is the DSCR, not the LTV. Whatever the LTV is, the cashflow is what stops you first. We only count on current rents and use very conservative growth assumptions.
You do bridge loans, as I understand it. What types of assets is that appropriate for? Can you back land deals?
Šafránková: Yes, but selectively — if there’s a strong sponsor, with a quality locality. Bridge loans can be used for the acquisition of land where the permits aren’t in place yet, but the project is in line with the master plan. Or for a project that isn’t ready for senior financing. They can also cover the acquisition of a building that will be converted, for example, from office to residential. We can grant a one- to two-year bridge loan and then convert it into a development or investment loan. We just have to check each drawdown against the expected future value.
What’s your read on the Prague office market? Are you willing to lend?
Šafránková: We understand that headline rents need to reach at least €24 per sqm/month for new office developments in order to make financial sense. This floor has risen for developers because construction costs, financing costs and land costs have all increased significantly. Most developers tend to be optimistic about achieving that number, but we have to be careful.
On the other hand, there will still be a market for B-class offices in good locations at €15 or €16 for tenants who don’t need a triple-A buildings. Some companies don’t need a green-lease for their branding and they’re happy to stay where they’ve been for the past five or ten years. Location and employee comfort matter most to them.
Where’s the line between a functioning B-class building and a zombie asset on the edge of collapse?
Vančura: It’s location, the sponsor, current tenants, and the CAPEX plan. The real question is the building’s actual and future positioning in the rental market. The right rent attracts the right tenant. As Rita says, a B-class building doesn’t stop working automatically because it’s older.
Czech yields are the lowest in CEE. Is that justified?
Vančura: There’s very strong local demand from local investors, because there’s a lot of fund money and bond money in the market. This more than offsets the diminishing foreign investment. It shows trust in the local market and in political stability here. The question is to what extent it’s technically justified. I am conservative on this.
What’s missing is an investment alternative for Czechs because we don’t have alternatives like a stock exchange here with enough liquidity and titles. With property, people can see the buildings, they see the quality. Savings are at a historical maximum. The money is in the economy.
Where do you see interest rates heading?
Vančura: The conflict in the Middle East killed the hopes for decreasing rates. Central banks are afraid of rising inflation and the longer the conflict continues, the higher the risk of further increases. It’s as simple as that.
You’ve mentioned wanting to increase your exposure to hotels. What’s the attraction for you. It seems a bit unusual for a bank your size.
Šafránková: Not every bank wants to finance hotels, so there’s less competition. We are already active in this segment on a selective basis, and we want to increase our market share. The underwriting is different — you’re looking at revenue per room, seasonality, operator quality — but Prague is a strong hotel market and we understand it. It also fits our approach, which is to find sectors where we can be selective and add value, rather than fight on margin alone.
You say you’re conservative, but your strategy and your goal of doubling your loan book is pretty aggressive.
Šafránková: We have the plan and the appetite to increase our volume. Due to the increased capital we can bid on bigger volumes of financing, where we can offer flexibility, individual approach, and competitive conditions We are here and we are ready to finance new projects and new groups. We can afford it.
Also in ThePrime
Tomáš Kadeřábek (Assoc. of Developers): A giant leap for planning!
Miroslav Barnas (ARETE): C. European logistics still the best yield opportunity