
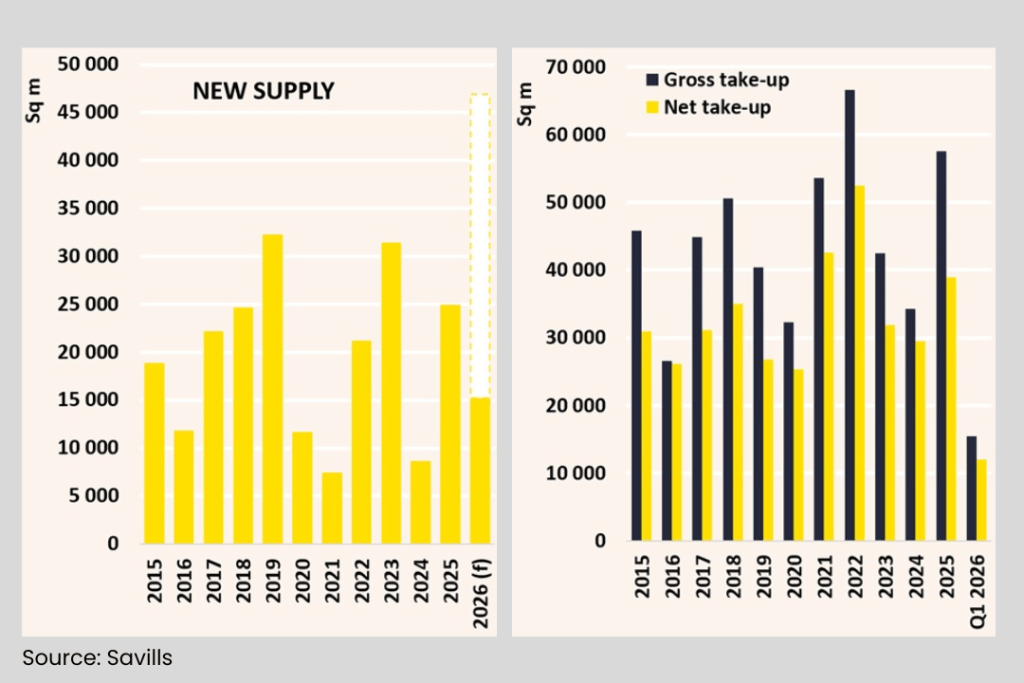
Czech developers will deliver an estimated 46,900 sqm of Small Business Unit space this year, making 2026 the sector’s second-strongest on record. Only 2007 saw more. The data comes from a Savills analysis of Grade A industrial units capped at 1,000 sqm GLA.
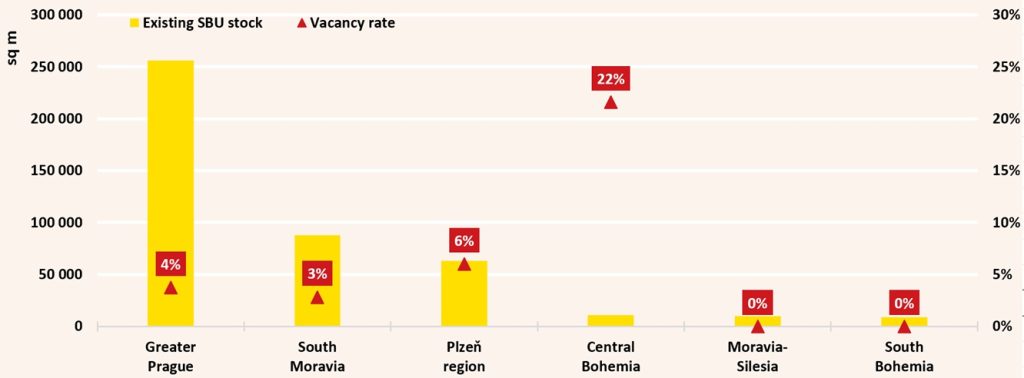 Supply is the constraint, not demand. In fact, Savills found leasable SBU space in just four of the country’s 14 regions. Five regions still have none at all. Nationwide vacancy sat at 4.1% in March, with new units vanishing almost immediately after they come on-line. Net take-up jumped to 38,900 sqm in 2025, with another 12,000 sqm of supply appearing in Q1 2026. Savills says those it’s likely that current take-up figures undercount real demand because no deals can close where no space exists.
Prague holds 58% of the country’s 439,400 sqm total SBU stock. South Moravia follows at 20%, Pilsen at 14%. Headline warehouse rents range from €8.50 to €12.25 per sqm per month, with Prague inner-city schemes commanding the top end and regional markets sitting between €7.50 and €9.50.
A significant pipeline is building. Some 31,700 sqm was under construction or at shell-and-core stage as of March, 39% of which is already pre-let. Beyond that, roughly 410,000 sqm is working through planning and permitting. “There is strong demand from international companies entering the Czech market,” says Lenka Kocianová, Industrial Consultant at Savills, adding that older industrial premises are increasingly being demolished or repurposed for residential, forcing tenants toward modern stock.
Also in ThePrime
Pavel Velebil (Tide Reality) describes the 4 types of investment flat buyers
EU customs crackdown turns Chinese parcel flood into warehouse demand
Martin Baláž (Prologis): We can develop 180,000 sqm around Prague